
AEP Starts October 15. Your Medicare Review Shouldn't.

Bob Wisecarver
Don't Wait for Open Enrollment. Let's Talk Now.
Every fall, Medicare's Annual Enrollment Period (AEP) rolls around, and with it comes a flood of TV commercials, mailers stuffed in your mailbox, and robocalls that seem to never stop. It can feel overwhelming, even if you've been on Medicare for years.
Here's the good news: it doesn't have to be that way. If you're open to a quick conversation now, before any of that noise starts, we can take care of everything together so that by the time AEP arrives, you're already done.
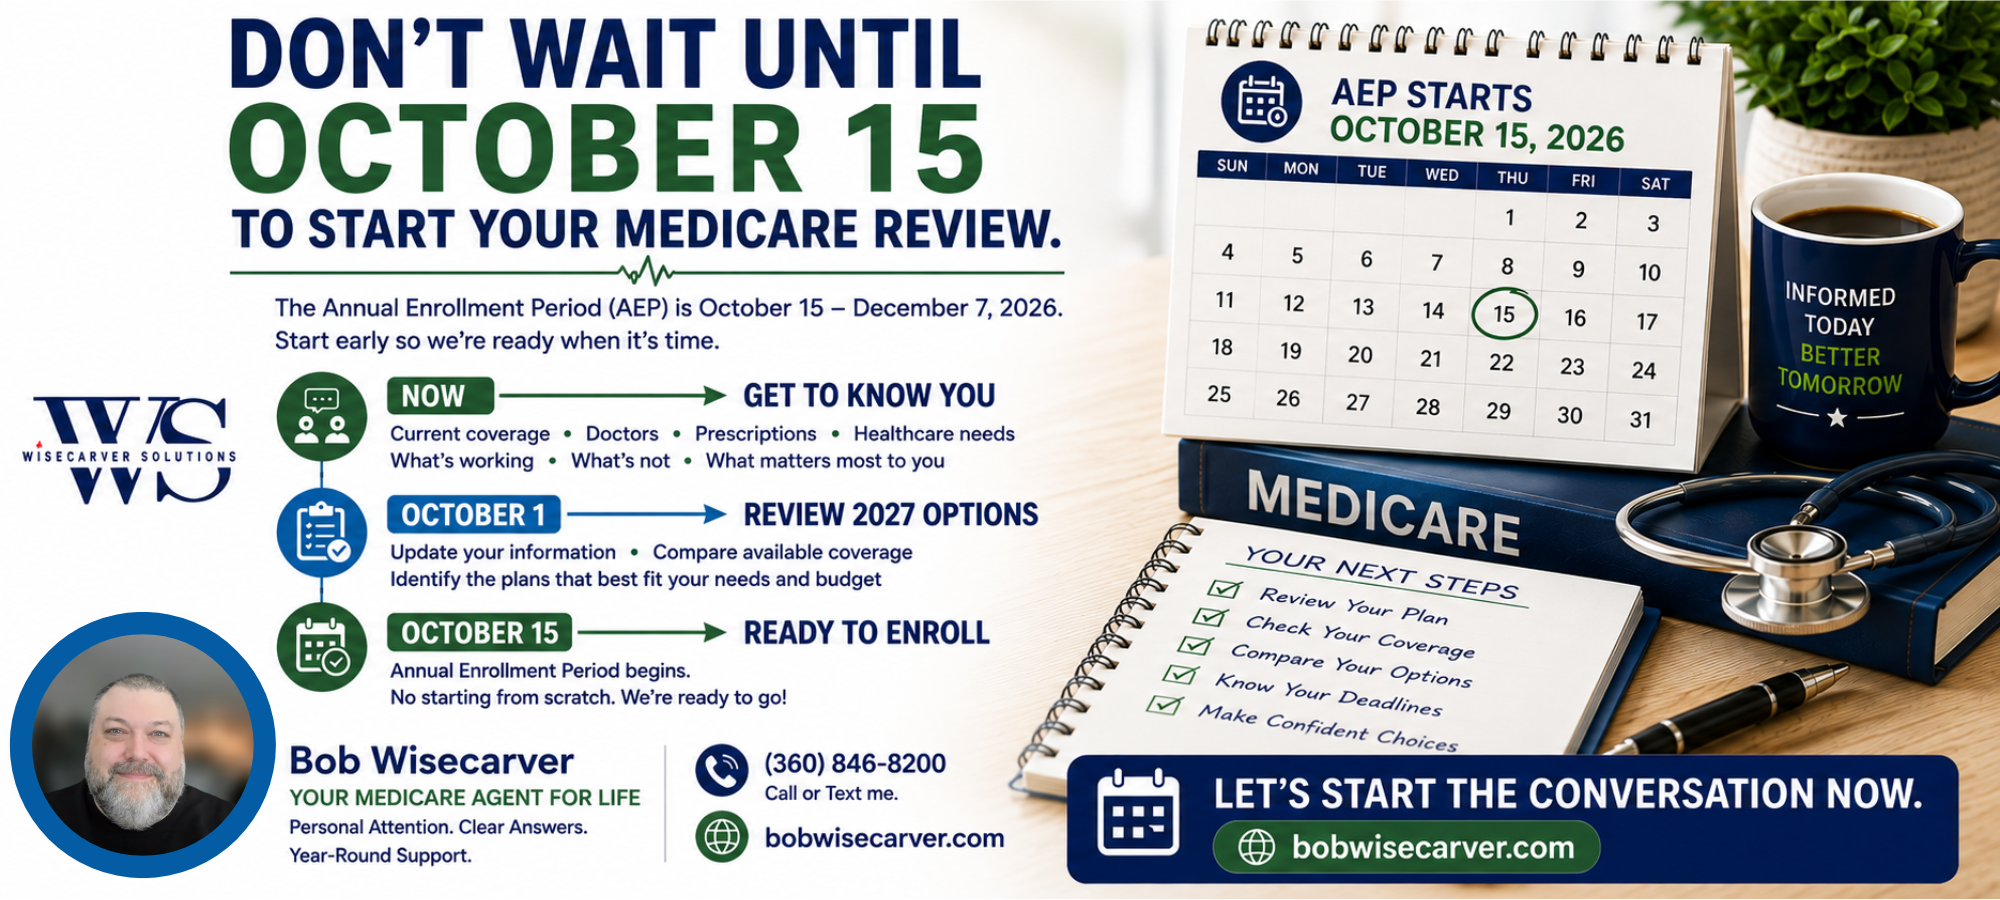
Here's how the process works, in three simple steps. See the graphic below for a visual look at the timeline.
Step 1: A Conversation Now
We start with a relaxed, get-to-know-you call. There's no pressure and nothing to sign. I just want to learn about your situation: your doctors, your medications, your current plan, and what matters most to you when it comes to your health coverage. You get to know me, too. By the end of the call, I'll have a clear picture of what you need and whether there's anything I can help you with right now.
Step 2: A Review Call on October 1
October 1 is when the new 2027 Medicare plans become available for review. Once those are released, I'll go through your options and compare them against everything I learned about you in our first conversation. My goal is to identify the best plan for your situation before enrollment even opens. That way, we're not scrambling or guessing when the clock starts ticking.
Step 3: A Short Final Call During AEP (October 15 to December 7)
This is the easy part. Annual Enrollment runs from October 15 through December 7 — this is the window when you can make changes to your Medicare coverage, with those changes taking effect January 1. Because we've already done the homework, this call is short. We simply confirm your plan and complete the enrollment. It takes minutes, not hours.
The Payoff: You're Done
Once you're enrolled, you can tune out the sales noise entirely. The commercials, the unsolicited mailers, the robocalls from carriers you've never heard of — you can ignore all of it with confidence, because someone who knows your situation already took care of it for you. (Just keep an eye out for anything that actually comes from your own plan or Social Security — that's different from marketing noise, and it's still worth a quick read.) No confusion. No second-guessing. Just peace of mind going into the new year.
What's Changing with Part D in 2027 (And Why It Matters)
If you take prescription medications through Medicare, there's an important change coming in 2027 that's worth understanding now, especially if you currently receive Extra Help with your drug costs.
Here's some background. For the past two years, Medicare's governing body (CMS, the Centers for Medicare and Medicaid Services) has run something called the Premium Stabilization Demonstration — a temporary program that reduced base Part D premiums and capped how much they could increase year to year, helping keep prescription drug plan premiums lower than they otherwise would have been.
CMS has confirmed that demonstration ends after 2026. Starting in 2027, insurance companies will no longer receive that support, and many are expected to raise their Part D premiums to make up the difference.
For many people, this will simply mean a somewhat higher monthly premium. But for people who receive Extra Help, the stakes are a little more specific, so let me explain that program quickly.
Extra Help (also called the Low-Income Subsidy, or LIS) is a federal benefit that helps pay your Part D drug plan premium. It covers your premium up to a regional benchmark amount set each year by Medicare. If your plan's premium is at or below that benchmark, Extra Help covers it completely and you pay nothing. If the premium rises above the benchmark, you're responsible for the difference out of pocket, even with full Extra Help.
Here's a hypothetical situation to explain how that works. In Washington and Oregon, the 2026 benchmark is $10.46 per month. If a plan priced below that benchmark this year raised its premium to, say, $30 per month, an Extra Help recipient would owe roughly $19.54 per month out of pocket — money they weren't paying before, showing up as a surprise bill in January. (CMS will set a new benchmark for 2027 later this year, so the exact numbers will shift — but the mechanism stays the same: if your plan's premium climbs above whatever that new benchmark turns out to be, you'll feel it.)
The most important thing to understand is this: Extra Help isn't going away. Your benefits aren't being cut. The program still exists and still works the same way it always has. What's changing is that the plans themselves may become more expensive, and Extra Help only covers up to a certain point.
This is exactly why a review conversation before AEP matters. If your current plan raises its premium above the benchmark, there may be another plan that stays within your coverage and costs you nothing. The only way to know is to look — and that's what I'm here to help you do.
(This is general information to help you understand what's changing, not a quote or guarantee for any specific plan. Actual premiums and benchmark amounts for 2027 will be confirmed by CMS later this year.)
Ready to Get Ahead of It? Let's Talk.
If anything in this post made you think, "I should probably take a closer look at my coverage," I'd love to hear from you. Head over to bobwisecarver.com to set up an appointment, or just call or text me directly at (360) 846-8200. It's easy, it's free, and there's absolutely no pressure. It's just a conversation, and it could save you a real headache come January.